


India's Property Market Weighs Higher Rates Against Long-Term Growth Prospects
India’s real estate sector faces a fresh test as higher borrowing costs and inflationary pressures reshape the outlook for residential, commercial, retail and hospitality assets. The Reserve Bank of India’s 25-basis-point repo rate increase to 5.5% has renewed questions around housing affordability, financing costs and investment decisions. The shift in the monetary policy stance from Neutral to Calibrated Tightening has also brought the trajectory of interest rates into sharper focus. India’s property market balances rising borrowing costs with long-term growth opportunities The implications for real estate will depend on how higher financing costs interact with household purchasing power, corporate investment and demand across individual markets. While more expensive borrowing could affect affordability and the timing of property purchases, industry executives point to end-user demand, infrastructure development and expanding business activity as factors supporting the sector’s longer-term prospects. The impact is unlikely to be uniform across asset classes. Residential property is particularly sensitive to mortgage affordability, while commercial real estate depends on corporate expansion, occupier demand and investment appetite. Hospitality-led developments, meanwhile, are influenced by tourism flows and the economic activity of individual destinations. Uddhav Poddar, CMD, Bhumika Group, said, “The RBI’s decision to raise the repo rate is a measured response to the renewed inflationary pressures from elevated crude prices and the evolving global financial environment. From a real estate perspective, the impact will be felt primarily through borrowing costs, liquidity and the transmission of rates across the financial system. However, the broader economic backdrop remains encouraging." “For residential real estate, higher financing costs may influence affordability and purchase decisions at the margin, but end-user demand remains anchored by long-term housing requirements. In commercial real estate, investment decisions are influenced by a broader set of factors, including business expansion, employment, capital flows and institutional appetite, and these fundamentals remain constructive. While the financial markets will continue to assess the implications of a calibrated tightening cycle, we believe a measured rate adjustment by itself does not alter the long-term investment case for Indian real estate. The sector’s underlying fundamentals remain positive, and the key will be how inflation, liquidity and interest rates evolve from here,” he added. For commercial real estate, the outlook remains closely linked to occupier demand and business expansion. Companies evaluating office and retail spaces typically consider long-term operational requirements alongside financing conditions, while infrastructure improvements can strengthen the appeal of established commercial destinations. Dr. Amish Bhutani, Managing Director, Group 108, said, “The RBI’s decision to raise the repo rate by 25 basis points to 5.50% reflects a cautious approach towards managing inflation while maintaining economic momentum. For the commercial real estate sector, the impact is likely to be measured, with businesses continuing to evaluate expansion plans based on long-term fundamentals. Strong demand for quality office and retail spaces, coupled with improving infrastructure and business activity, would continue to support leasing and investment interest across established commercial destinations.” Housing demand faces the affordability test In residential markets, the relationship between interest rates and demand is more direct. Higher borrowing costs can increase monthly mortgage payments and affect purchasing power, particularly among buyers who are more sensitive to changes in financing costs. Developers, however, argue that long-term housing requirements and the preference for better-connected, quality developments continue to support demand. In Chandigarh and the surrounding Tricity region, established social infrastructure, improving connectivity and an end-user-driven market remain important considerations for homebuyers. Location, construction quality, lifestyle amenities and long-term value are increasingly influencing purchasing decisions. Abhay Jindal, Managing Director, Homeland Group, said, “The RBI’s decision to increase the repo rate by 25 bps and move its policy stance from Neutral to Calibrated Tightening comes at a time when global developments are creating renewed inflationary pressures, particularly through crude prices. The change in stance provides clarity on the RBI’s approach while India’s domestic economy continues to show resilience. For the residential market, the strength of domestic demand remains important. Homebuyers are making decisions based on their long-term requirements
India’s real estate sector faces a fresh test as higher borrowing costs and inflationary pressures reshape the outlook for residential, commercial, retail and hospitality assets. The Reserve Bank of India’s 25-basis-point repo rate increase to 5.5% has renewed questions around housing affordability, financing costs and investment decisions. The shift in the monetary policy stance from Neutral to Calibrated Tightening has also brought the trajectory of interest rates into sharper focus.
|
|
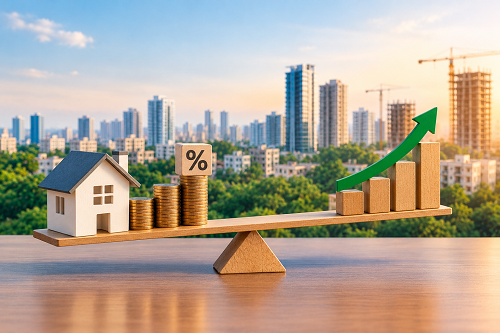
India’s property market balances rising borrowing costs with long-term growth opportunities
The implications for real estate will depend on how higher financing costs interact with household purchasing power, corporate investment and demand across individual markets. While more expensive borrowing could affect affordability and the timing of property purchases, industry executives point to end-user demand, infrastructure development and expanding business activity as factors supporting the sector’s longer-term prospects.
The impact is unlikely to be uniform across asset classes. Residential property is particularly sensitive to mortgage affordability, while commercial real estate depends on corporate expansion, occupier demand and investment appetite. Hospitality-led developments, meanwhile, are influenced by tourism flows and the economic activity of individual destinations.
Uddhav Poddar, CMD, Bhumika Group, said, “The RBI’s decision to raise the repo rate is a measured response to the renewed inflationary pressures from elevated crude prices and the evolving global financial environment. From a real estate perspective, the impact will be felt primarily through borrowing costs, liquidity and the transmission of rates across the financial system. However, the broader economic backdrop remains encouraging."
“For residential real estate, higher financing costs may influence affordability and purchase decisions at the margin, but end-user demand remains anchored by long-term housing requirements. In commercial real estate, investment decisions are influenced by a broader set of factors, including business expansion, employment, capital flows and institutional appetite, and these fundamentals remain constructive. While the financial markets will continue to assess the implications of a calibrated tightening cycle, we believe a measured rate adjustment by itself does not alter the long-term investment case for Indian real estate. The sector’s underlying fundamentals remain positive, and the key will be how inflation, liquidity and interest rates evolve from here,” he added.
For commercial real estate, the outlook remains closely linked to occupier demand and business expansion. Companies evaluating office and retail spaces typically consider long-term operational requirements alongside financing conditions, while infrastructure improvements can strengthen the appeal of established commercial destinations.
Dr. Amish Bhutani, Managing Director, Group 108, said, “The RBI’s decision to raise the repo rate by 25 basis points to 5.50% reflects a cautious approach towards managing inflation while maintaining economic momentum. For the commercial real estate sector, the impact is likely to be measured, with businesses continuing to evaluate expansion plans based on long-term fundamentals. Strong demand for quality office and retail spaces, coupled with improving infrastructure and business activity, would continue to support leasing and investment interest across established commercial destinations.”
Housing demand faces the affordability test
In residential markets, the relationship between interest rates and demand is more direct. Higher borrowing costs can increase monthly mortgage payments and affect purchasing power, particularly among buyers who are more sensitive to changes in financing costs. Developers, however, argue that long-term housing requirements and the preference for better-connected, quality developments continue to support demand.
In Chandigarh and the surrounding Tricity region, established social infrastructure, improving connectivity and an end-user-driven market remain important considerations for homebuyers. Location, construction quality, lifestyle amenities and long-term value are increasingly influencing purchasing decisions.
Abhay Jindal, Managing Director, Homeland Group, said, “The RBI’s decision to increase the repo rate by 25 bps and move its policy stance from Neutral to Calibrated Tightening comes at a time when global developments are creating renewed inflationary pressures, particularly through crude prices. The change in stance provides clarity on the RBI’s approach while India’s domestic economy continues to show resilience. For the residential market, the strength of domestic demand remains important. Homebuyers are making decisions based on their long-term requirements, and a single rate increase is unlikely to alter that underlying demand.”
Tejpreet Singh Gill, Managing Director, Gillco Group, said, “The RBI’s decision to increase the repo rate comes at a time when inflationary pressures and crude prices have again become a concern. However, the fundamentals driving real estate remain intact. Demand today is increasingly coming from genuine end users, supported by urbanisation, infrastructure development and improving connectivity. These factors are not altered by a single movement in the repo rate.”
Vishal Goyal, Director, Highland LifeSpaces, said, “While the repo rate hike may have a near-term impact on borrowing costs and buyer sentiment, we expect housing demand to remain resilient. In the Tricity, strong end-user demand, improving connectivity and continued infrastructure development are supporting the residential market. Homebuyers are increasingly taking a long-term view, prioritising location, quality and lifestyle over short-term interest-rate movements.”
Across Punjab, infrastructure investment and connectivity are also shaping buyers’ assessment of residential property. However, the extent to which these factors offset higher financing costs will depend on local affordability, property prices and the strength of end-user demand.
Varun Baweja, Director, Fomerah Ventures Pvt. Ltd., said, “The RBI’s 25-basis-point repo rate hike to 5.50% may have a marginal near-term impact on borrowing costs, but we believe housing demand in Punjab will remain resilient. Buyers are increasingly taking a long-term view, with quality, location, connectivity and value emerging as key considerations. With improving infrastructure and steady end-user demand, Punjab’s residential market continues to have strong fundamentals for sustained growth.”
Emerging cities offer a different growth equation
Beyond established residential markets, emerging destinations are attracting interest through urbanisation, improving connectivity and changing consumer preferences. Dehradun’s appeal is linked to evolving lifestyle aspirations and infrastructure development, while Shirdi’s pilgrimage economy is creating opportunities in hospitality and related real estate.
Manit Sethi, Director, Excentia Infra, said, “The RBI’s 25-basis-point repo rate hike to 5.5% reflects a calibrated approach towards maintaining economic stability while addressing inflationary pressures. We remain positive about the real estate sector, particularly in emerging cities such as Dehradun, where improving infrastructure, connectivity, urbanisation and rising aspirations are driving sustained housing demand. While interest rates may influence financing decisions in the short term, the fundamentals of these markets remain strong. We believe quality developments in well-connected locations will continue to attract both end-users and long-term investors.”
In Shirdi, demand is more closely tied to visitor flows and the need for accommodation and related services. Developers are exploring differentiated assets that respond to changing visitor preferences, although their long-term performance will depend on sustained demand, operating models and the quality of execution.
Neeraj Gulati, Managing Director, Assotech Realty, said, “The RBI’s 25-basis-point repo rate hike to 5.5% reflects the need to balance inflationary pressures with sustained economic growth. While higher borrowing costs may create some near-term pressure on financing and consumer sentiment, we believe the long-term outlook for real estate and hospitality remains positive. Pilgrimage destinations continue to benefit from strong pilgrimage-led footfall and evolving tourism demand. For developers, the focus will remain on creating quality, differentiated assets that offer enduring value and support the growth of emerging destinations.”
Retail and commercial property adapt to changing demand
Retail and commercial real estate are also being reshaped by changing occupier requirements and consumer behaviour. Retailers increasingly seek locations that combine accessibility with customer engagement, while businesses assess commercial spaces on functionality, operational efficiency and the quality of their surrounding ecosystems.
Azad Ahmed Lone, President, Biigtech, said, “The RBI’s 25-basis-point repo rate hike to 5.5% reflects confidence in the underlying strength of the Indian economy. For the retail and commercial real estate sector, the outlook remains highly encouraging, supported by rising consumer spending, expanding businesses and increasing demand for quality commercial spaces. We are witnessing a clear evolution towards experience-led retail and professionally managed commercial assets, creating new opportunities for investors and occupiers alike.”
The outlook for Indian real estate will depend on how monetary policy interacts with household purchasing power, corporate investment and demand across individual markets. Higher rates could weigh on affordability and delay some transactions, while infrastructure development, urbanisation and the demand for quality assets may continue to support activity.
For developers, the challenge will be to balance project costs, pricing and execution with buyers’ ability to absorb higher financing costs. The sector’s resilience will ultimately depend not simply on its response to monetary policy, but on the depth of underlying demand and its ability to deliver developments that meet the needs of homebuyers, occupiers and visitors.